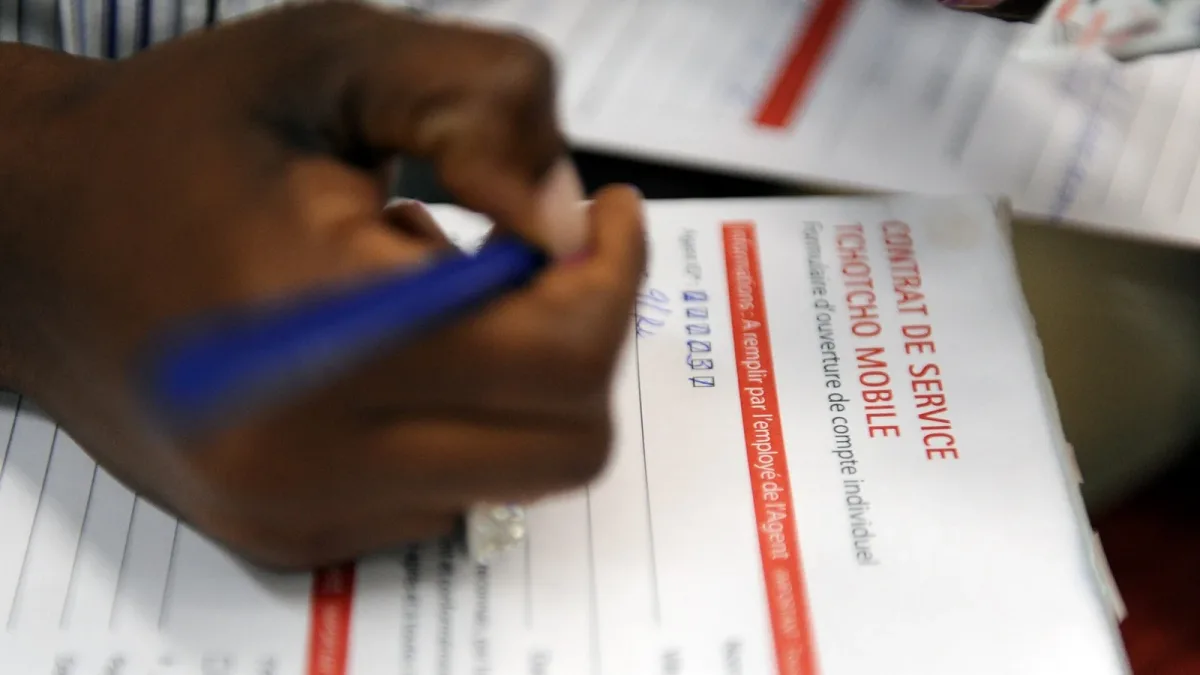
An order may expire before an interbank transfer appears in the recipient's account.
A banking form illustrates how references and timestamps can clarify expired transactions.
Where order deadlines enters the decision
The buyer's application says sent, while the seller's balance and the escrow timer tell a different story.
What transfer timing can establish
Order deadlines are workflow limits, whereas payment settlement is controlled by the financial network. Instant transfer labels do not eliminate delays, name checks, bank maintenance or pending review. A platform may have its own process for handling late receipts.
An example involving order deadlines
A transfer initiated at the final minute of a P2P order may appear after the timer reaches zero. The buyer should not automatically make a second transfer, and the seller should not automatically release. Preserve the original order, confirm the receiving account, and use the platform's approved late-payment procedure. The role of transaction references in delayed settlement is developed in matching payment references across systems.
The order clock and the payment clock are different
A marketplace timer describes the period in which participants must act under the order; a bank settlement process may operate independently. Payment can be initiated before expiry yet credited afterward. The buyer's claim and the seller's balance may therefore differ without immediately establishing fraud. Time-zone conversions, banking interruptions and missing payment references can complicate reconciliation. The best record includes the original order deadline, the transfer initiation time, the final bank status and the recipient details so the difference can be investigated rather than guessed away.
A buyer who fears an expired timer might be tempted to send the same amount again or accept a new account supplied in chat. Either choice creates a second transaction without resolving the first. Instead record the initial transfer reference and consult the platform's documented late-payment steps. If a credit arrives after the order closes, match it to the original beneficiary and order. A visible timer is useful as an operational signal, but it is not an instruction to release crypto against unconfirmed bank evidence.
Practical checks before proceeding
Record the payment initiation time, its status in the sending institution and the order expiry time. Do not assume a new order automatically covers funds sent under the first. Request an approved extension or escalate before the evidence trail becomes fragmented.
- Preserve timestamps from both the marketplace and financial institution.
- Do not start a replacement transfer merely because a previous payment is late.
- Use the order's approved extension or dispute mechanism.
What can go wrong with order deadlines
A common mistake is creating a second payment to compensate for uncertainty. That doubles the amount exposed without proving where the first transfer went. Another is accepting private instructions to release funds after an expired order.
A practical decision rule for order deadlines
Treat the timer as an operational cue to preserve evidence and follow the platform's process. It should never replace verification that the money has actually arrived. A P2P crypto agent may discuss timing but cannot silently alter the marketplace's deadline or a bank's clearing rules. Shiftal Coin explains those boundaries.
#OrderDeadlines #TransferTiming #Escrow